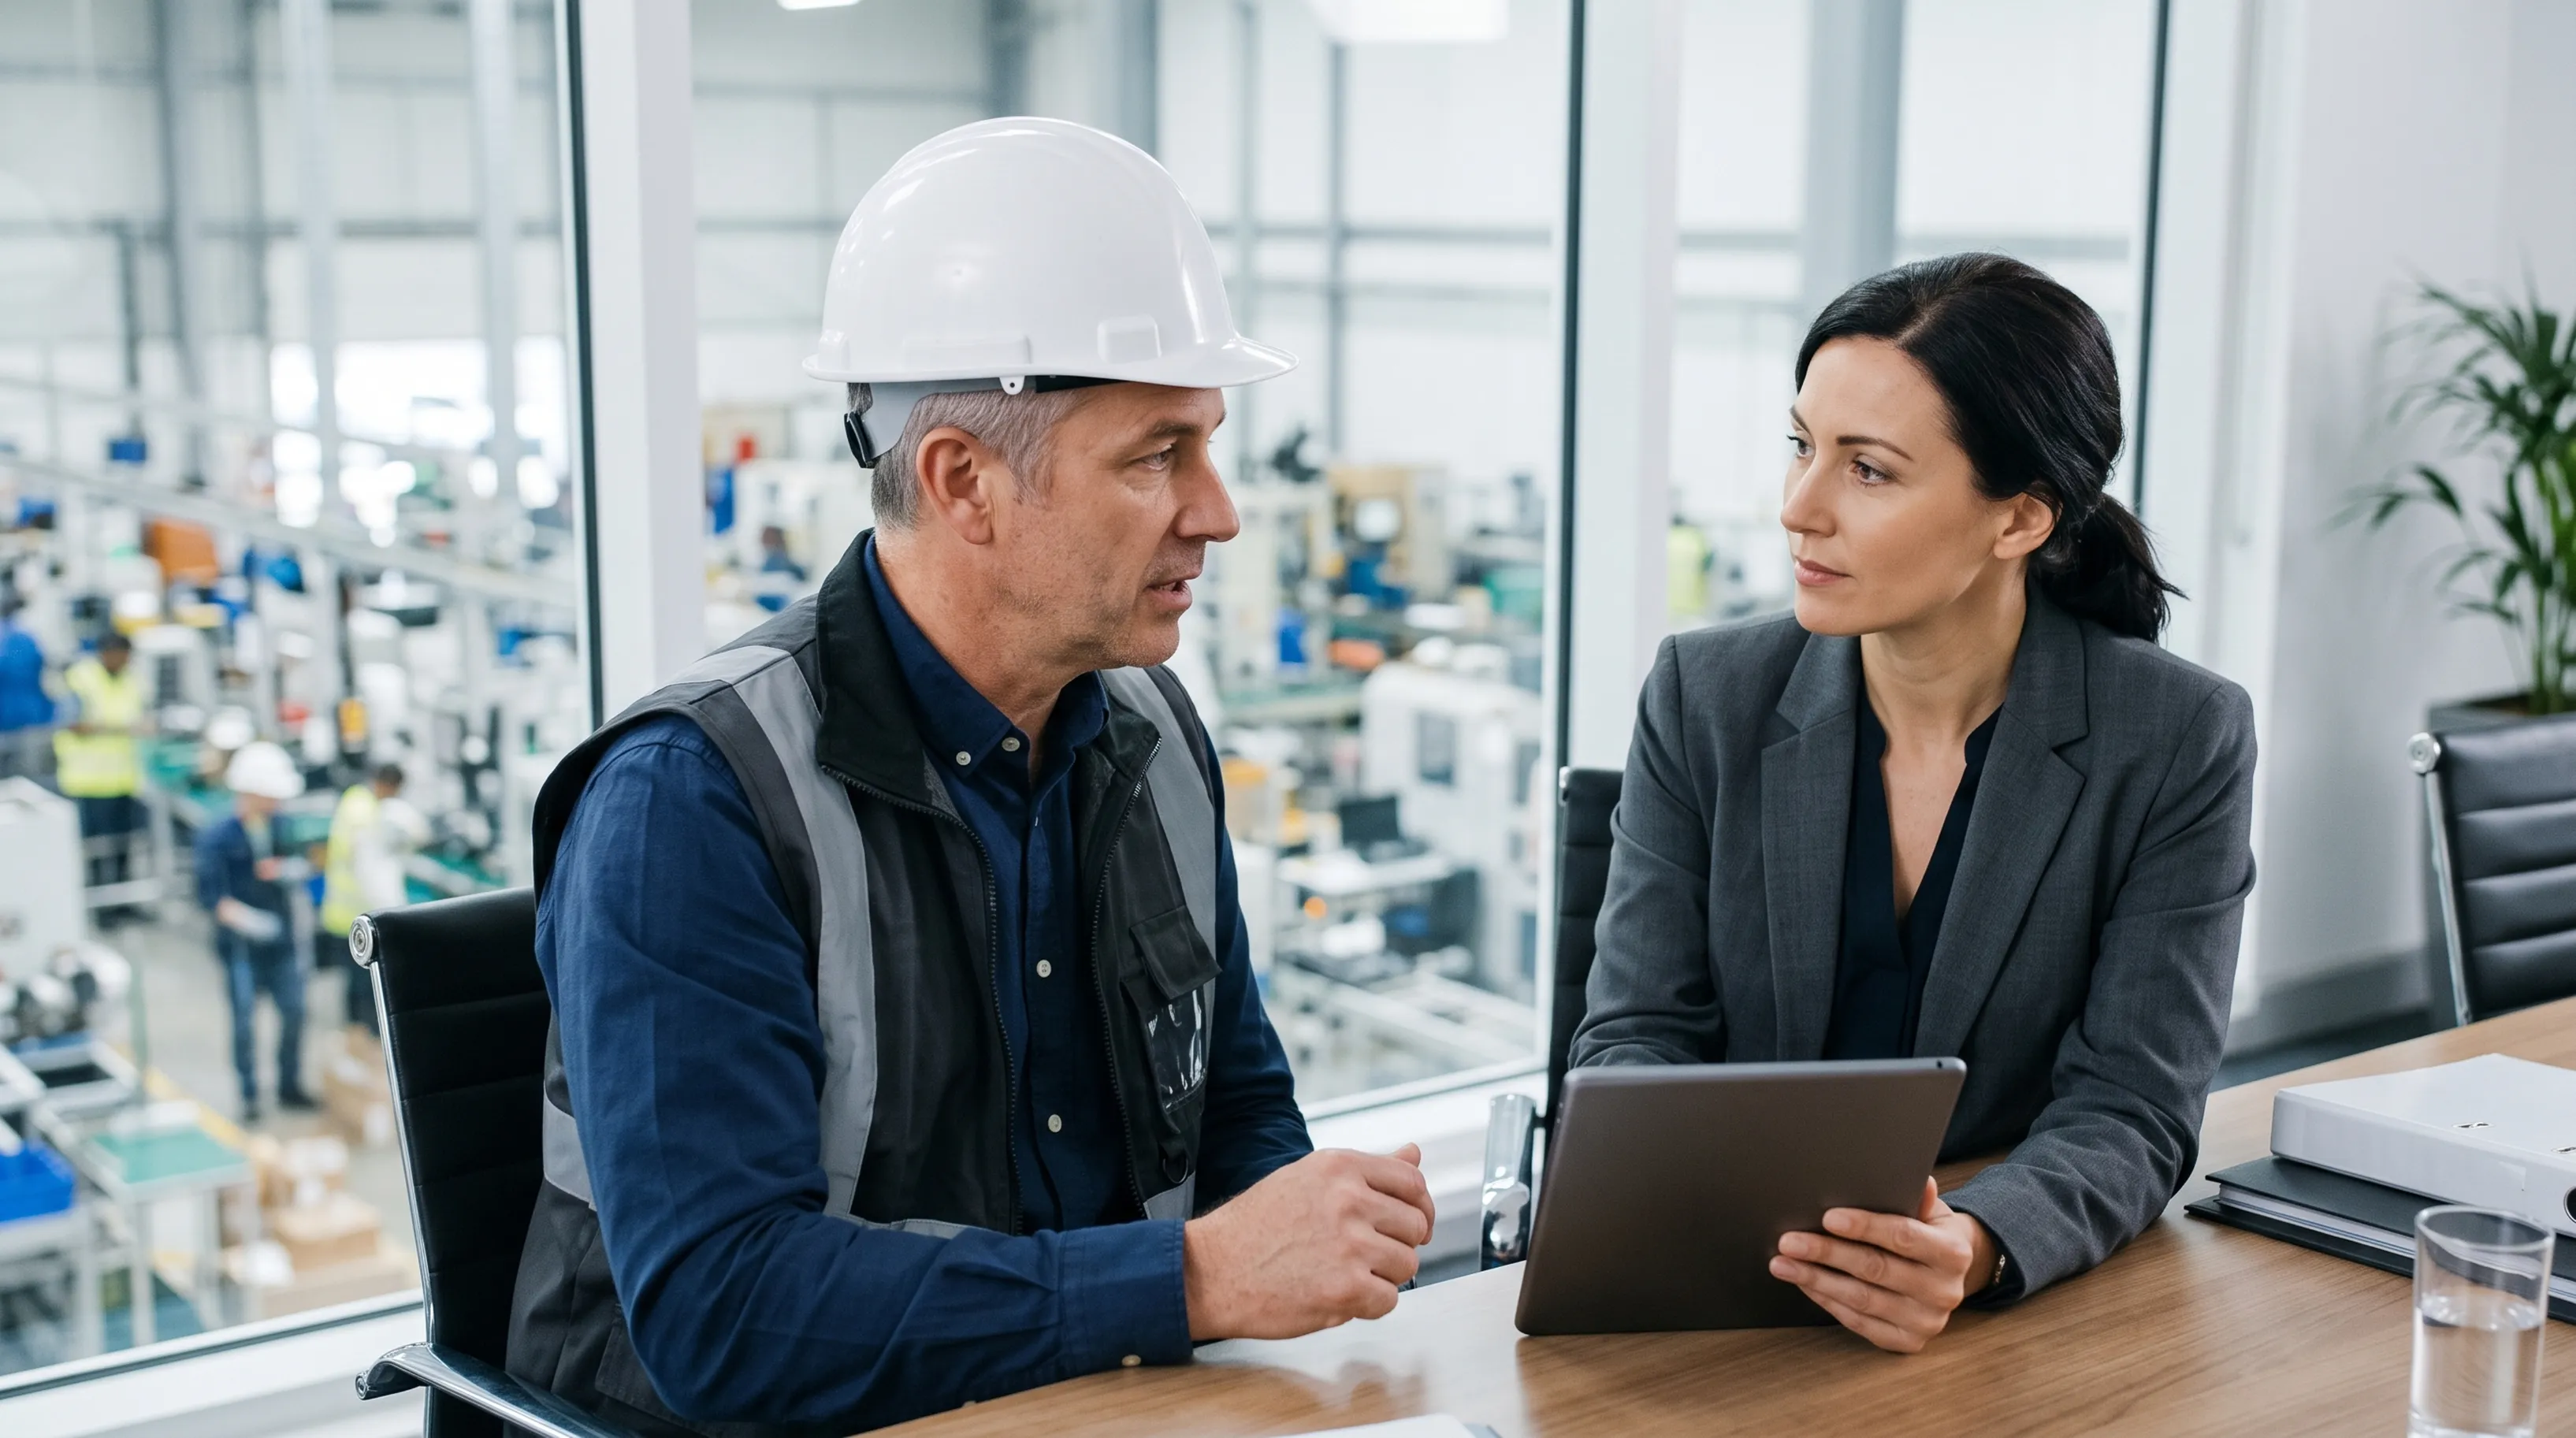


The Experience Modification Rate goes by many names: EMR, E-Mod, MOD Rate, Experience Rating, or Experience Modification Rate. But regardless of what term you use, it’s a very important one to understand—especially as it relates to those that your organization does business with on a regular basis. This rate is a number used by insurance companies to determine past costs of things like injuries and also future opportunities for risk. If a rating is 1.0 or greater, then it’s important that you and your team understand the potential risks of working with those vendors or contractors.
In this article, we’ll explore what the Experience Modification Rate is, how it applies to your organization, and how it’s possible for your vendors and subcontractors to obtain a more attractive risk rating so your organization can rest easier when working with those third parties.
What Is The Experience Modification Rate?
Optimum Safety Management explains that the Experience Modifier Rate is a numbered rating that represents a business’s claims history and safety record as compared to other businesses in the same industry, within the same state. For example, a plumbing contractor in California would be compared with other plumbing contractors in California.
The EMR basically places a company in one of three categories:
- This company is riskier than average (EMR > 1.0)
- This company is no more or no less risky than average (EMR = 1.0)
- This company is safer than average (EMR < 1.0)
The rating takes into account the number of previous incidents, the type of incident (medical vs. time lost), and the amount of money paid out for each incident.
Why Does It Matter To Your Organization?
As your organization does business with vendors and subcontractors, their MOD rate should be considered before you accept their bid on a project. If, for instance, a contractor puts in a competitive bid for a project but they have a high Experience Modification Rate, then perhaps you should evaluate other vendors and contractors before making the final decision. You may not only find a lower bid, but if the contractor has a history of claims, accidents, and time lost on the job site due to incidents, your organization is taking on additional risk by entering into contract with the entity.
Can Vendors & Contractors Lower Their Risk?
Yes, fortunately it is possible for your vendors and contractors to lower their EMR. However, the process is long and usually starts with a detailed safety plan and in depth analysis. Organizations that are serious about lowering their rate will invest in employee training to ensure every subcontractor is safe on the job.
Risks are present in every circumstance and accidents do happen no matter how careful a company may be to ensure their subcontractors have all of the tools and knowledge they need. It’s up to your organization to assess the level of risk in a certain vendor and determine if your organization should work with that organization. Just keep in mind that there may be a reason their bids are so low and attractive! Make sure nothing slips past you before signing for a project!
Let Lumie handle the paperwork
Keeping every certificate current is a lot to ask of any team. illumend, from myCOI, reads each certificate and endorsement against your requirements, flags what’s missing, and follows up with your third-party partners for you. You’ll see who’s covered, and who isn’t, without chasing a single email.
Want to see it in your workflow? Schedule a demo and we’ll show you how illumend fits.